The post AI in Research: Coding Qualitative Data appeared first on GeoPoll.
]]>Before any of that text becomes an insight, someone has to code it.
Qualitative coding is the process of reading through unstructured responses and assigning labels, or codes, to segments of text so the data can be organized and analyzed. A response such as “the clinic was far and the queue took all morning” might be coded for distance, waiting time, and access to services. If you multiply that by 20,000 responses in five languages, you begin to see the problem.
We have covered the fundamentals of this process before in our guide to coding qualitative data. In this post, we look at what AI adds to the workflow.
How data coding works
There are two main approaches to coding qualitative data:
- Deductive coding begins with a codebook built in advance, usually from the research objectives or an earlier wave of the same study. Coders apply the existing labels to incoming responses. It is quicker and keeps findings comparable across waves, but it can miss themes nobody thought to look for.
- Inductive coding begins with the data. Coders read the responses, allow categories to emerge, and build the codebook as they go. It catches the unexpected, which is often where the real insight sits, but it takes longer and depends heavily on the coder.
In practice, most studies combine the two: a starting framework drawn from the objectives, then expanded as the data reveals themes the framework did not anticipate.
Why manual coding can be a bottleneck
The method itself is sound, but the constraint usually is human capacity.
An experienced researcher can code 500 responses in an afternoon. However, coding 50,000 responses across six countries is a different ballgame. And as volume grows, three problems compound.
The first is drift. The same coder applies a code slightly differently at response 4,000 than they did at response 40, usually without realizing it.
The second is disagreement. Two coders reading the same response will not always reach the same conclusion, which is why inter-coder reliability has to be tested, trained for, and tested again. That is more time on top of the coding itself.
The third is language. Taking the countries GeoPoll works in as an example, a single study might collect responses in Swahili, French, Spanish, Hausa, Arabic and English. Sometimes more. Each language needs coders fluent in it, and maintaining consistency across those teams is harder still.
Most researchers are familiar with the result – it takes a long, long time.
What AI brings to the process
As we have experienced at GeoPoll, large language models are good at the exact task coding requires: reading a passage of text and determining what it is about. But AI coding quality depends far less on the model itself than on how you set it up and manage it. Pointing a general-purpose chatbot at 20,000 responses and asking it to “find the themes” will rarely produce accurate output.
Used well, AI coding is a structured process. It starts with a codebook grounded in the research objectives and clear instructions that define each code, with examples of what belongs under it and what does not. Where the volume or specialization justifies it, models can be fine-tuned on previously coded data from similar studies, so they learn the categories and language patterns that matter in a given sector or market. Prompts are tested and refined against a hand-coded sample before the full dataset is processed. And throughout, quality control stays in human hands: researchers check agreement rates, review low-confidence and edge cases, and audit a portion of the output on every run. Generally, experienced experts have to properly create and curate the models to function as they would.
When those pieces are in place, AI transforms qualitative coding, with several benefits:
- Speed: Thousands of responses can be coded in the time a team would spend on a few hundred. Analysis begins while the topic is still current.
- Consistency: A model applies the same codebook logic to the first response and the hundred-thousandth. It does not tire or lose focus, which removes the drift that manual coding has always had to absorb.
- Multilingual coverage: AI can code responses across languages without assembling a separate coding team for each one. For multi-country studies, this is often the single biggest gain.
- Theme discovery: Models can group responses and surface recurring patterns that a predefined codebook would have missed, including minority themes that tend to get flattened when a human coder is working at speed.
- Depth: Sentiment, intensity, and the reasoning behind a response can be captured alongside the code itself, giving researchers the why and not only the what.
- Cost: The cost of coding at scale falls sharply. This changes what is worth asking, and teams stop rationing open-ended questions to keep analysis manageable.
The challenges researchers should plan for
Like we have been saying, AI-powered research is not a substitute for research rigor. AI-assisted coding is no exception, because there are weaknesses to address.
- Nuance can be missed: Sarcasm, local idiom, and indirect phrasing can be read literally – a response that means the opposite of what it says can be misleading.
- Models can be confidently wrong: An undertrained AI will assign a code it cannot justify as readily as one it can, and the output looks identical either way.
- Bias can be inherited: Models reflect the patterns in their training data. In studies covering underrepresented populations and languages, this can determine which themes surface and which do not.
- Themes can be over-flattened: Aggressive grouping can collapse genuinely distinct ideas into one tidy category, losing the specificity that made the open-ended question worth asking.
- Data protection matters: Open-ended responses may often contain personal detail. Any AI workflow handling them requires informed consent, proper anonymization, and compliance with applicable data protection law.
- Transparency is not optional: If you cannot explain how a code was assigned, you will struggle to defend the finding to a client, a donor, or an ethics committee.
Best practices for AI-assisted coding
Keep a researcher in the loop. The goal is AI-assisted coding, not AI-only coding. Researchers should set the research frame, decide what the codes mean, review the output, and own the interpretation of the findings. The model handles the volume, but the judgment calls about what a theme means for the client, and whether a finding holds up, stay with people who understand the study and its context.
Start from a defined codebook. Give the model a clear framework tied to the research objectives rather than asking it to invent categories on its own. Each code should have a plain definition, a description of what belongs under it and what does not, and a few real example responses, including borderline ones. Where codes sit close together, such as the cost of a service and the cost of getting to it, spell out the difference. Let the model propose new themes as they emerge, but have researchers review and approve each addition, and keep a version history so you know which codebook was applied to which data.
Validate against a manual sample. Before processing the full dataset, have experienced coders hand-code a sample that reflects the range of countries, languages, and respondent groups in the study. Run the model on the same sample, compare the results, and measure agreement for each code rather than relying on a single overall score, which can hide a code the model consistently gets wrong. Where the two disagree, find out why, refine the instructions, and test again. Agree on an acceptable level of agreement before you start, and treat the model exactly as you would a new coder joining the team.
Write explicit instructions. Vague prompts produce vague codes. A good coding prompt reads like the briefing you would give a trained coder: it explains the research objective, the question respondents were answering, the full codebook, and how to handle responses that fit more than one code or none at all. It should include worked examples of difficult cases such as sarcasm, negation, and passing mentions. Asking the model to return the exact phrase that supports each code, along with a confidence level, makes errors easier to spot and speeds up review considerably.
Code in the original language. Translating first and coding second loses nuance twice over, once in translation and again in coding. Code responses in the language they were given, then translate the output for reporting. Test the model’s performance in each language separately, since a model that codes English and French well may struggle with Hausa or Amharic, and account for code-switching and informal language such as Sheng or Pidgin, which are common in open-ended answers. Native-speaker researchers should be part of the review process.
Review the edges. Check low-confidence codes, rare themes, fallback categories, and outliers closely. This is where errors concentrate, and it is often where the most interesting findings sit. Audit a random sample of high-confidence codes as well, since a model can be wrong with full confidence. Compare results across subgroups and batches, and look inside large themes to make sure they have not merged distinct ideas, such as staff attitude, waiting times, and stock shortages, into one broad label.
Document the method. Record the model and version used, the codebook and prompt versions, the validation results, and the human review process followed. Clients, donors, and ethics committees will ask how findings were produced, and documentation also makes it possible to reproduce results or apply the same setup consistently in the next wave of a tracking study. Data handling belongs here too: note how personal information was removed and where responses were processed.
Keep the verbatims. Codes are an abstraction of what people said, not a replacement for it. Keep every code linked to the original response so any finding can be traced back to the words behind it. Reading the verbatims behind the major themes is also how researchers move from counting mentions to understanding what respondents actually mean.
How GeoPoll approaches AI-Powered Coding
GeoPoll has collected data in Africa, Asia, and Latin America for over a decade, in markets and languages where fieldwork is most demanding. Open-ended questions have always been part of that work, and so has the coding bottleneck that follows.
Over the last few years, we have been training models in the methods we use, and the languages we work with, no matter how underserved they are. One result is GeoPoll Senselytic, our AI-powered qualitative layer built to transcribe open responses, analyze them for sentiment, themes, and patterns, and deliver results without requiring a coding team in every market. Our experienced researchers still control the codebook and the interpretation, to ensure the results are as actionable as they should be.
If coding open-ended responses is the step holding your projects back, contact us to discuss how Senselytic can fit into your research.
The post AI in Research: Coding Qualitative Data appeared first on GeoPoll.
]]>The post Research Report: Knowledge, Attitudes and Practices During the 2026 DRC Ebola Outbreak appeared first on GeoPoll.
]]>Against that backdrop, GeoPoll is publishing the findings of a nationwide Knowledge, Attitudes and Practices (KAP) study on the outbreak. We surveyed respondents across all 26 provinces of the DRC, covering knowledge of how Ebola spreads, perceptions of risk, attitudes toward survivors, information sources and trust, vaccine acceptance, protective behavior, burial practices, and belief in circulating rumors. Data collection closed on 16 September 2026, and the findings below are final.
This report, from 1,516 respondents, is free and is designed for the people running the response: risk communication and community engagement teams, health agencies, humanitarian implementers, and media covering the outbreak.
Ebola in the DRC: Some highlight findings
- Awareness is not a problem. 96% of respondents have heard of the outbreak. The communication challenge rests more on accuracy amid widespread miscommunication than on reach.
- We presented several statements to gauge transmission awareness, and while there is decent knowledge across most, one critical one is that only 20% know that a recovered survivor can still transmit the virus through certain body fluids, and two-thirds confidently hold the wrong answer.
- Stated acceptance of the response is high. 74% would take a vaccine if one became available for the current strain, and 88% would accept a trained burial team in protective equipment.
- Misinformation is dominated by uncertainty rather than firm false belief. 28% believe the virus was created in a laboratory by foreigners, and one in five believes salt water or herbal mixtures prevent infection. Across all five rumours tested, large shares answer “don’t know”, a persuadable middle that timely, trusted messaging can still reach.
- This misinformation has behavioral consequences. Respondents who believe the virus was created in a laboratory are three times more likely to refuse vaccination and five times more likely to turn to informal care first when illness strikes the household.
- Half the population is uneasy around survivors. 49% would be uncomfortable greeting someone who has recovered, and discomfort is highest where survivors are least familiar.
- The channels people use are not the ones they trust. Radio, television and social media deliver the widest reach, but health workers are the single most trusted source, and where they are deployed, behavior visibly changes.
The report also compares the five outbreak provinces with the rest of the country, showing where proximity to the epidemic changes knowledge, behavior and attitudes, and where it does not.
Download the free full DRC Ebola report
The full report includes detailed findings across nine thematic sections, an outbreak-zone analysis, and ten operational recommendations for the response. Fill in the form to download it for free.
Data dashboard
We have also published an interactive dashboard with breakdowns by province, gender, age, and area. It holds the final dataset from all 1,516 respondents, collected between 23 July and 16 September 2026.
The data is available to response organizations. GeoPoll will share the data behind this report with any organization working on the outbreak response, on request and at no cost, including cross-tabulations on any subset and the anonymized respondent-level dataset. Contact us at [email protected].
GeoPoll has conducted research through every major Ebola outbreak since 2014, from the West Africa epidemic through the eastern DRC outbreak of 2018 to 2020, and is currently delivering commissioned research inside the DRC. To discuss data collection needs, please contact us.
The post Research Report: Knowledge, Attitudes and Practices During the 2026 DRC Ebola Outbreak appeared first on GeoPoll.
]]>The post Research Report: Betting in Africa 2026 appeared first on GeoPoll.
]]>A six-country survey on who bets, what they play, how often, how they play, and how much they spend across Ghana, Kenya, Nigeria, South Africa, Tanzania, and Uganda.
Betting is one of the most active digital consumer categories in sub-Saharan Africa. In June and July 2026, GeoPoll surveyed 2,866 people across six of the continent’s largest betting markets to measure participation, product choice, frequency, channel, and spend. This report covers the survey questions, with country comparisons.
The headline is a market where betting is mainstream, runs overwhelmingly on mobile, and is played often. Beyond those constants, product choice and spending split the region into distinct markets. Football anchors betting almost everywhere, but South Africa runs on casino games instead. Kenya leans into fast crash-style games. Uganda spends the most per month. The takeaway for operators and advertisers is that a single continental strategy will misread most of these markets.
The findings sit inside a fast-growing industry. Industry estimates put Africa’s sports betting market at around 3 billion US dollars in 2025, with the wider gambling sector valued near 17.6 billion dollars and more than 440 million bettors across the continent. Cheap smartphones, expanding mobile internet, and widely used mobile money have turned betting into a mobile-first habit. This survey continues GeoPoll’s annual tracking of the category, building on our earlier Betting in Africa studies.
How many people bet
Betting participation is high across the region. Asked whether they had placed a bet in the past 12 months, between 54 and 64 percent of respondents said yes, led by Kenya at 64 percent and Ghana at 60 percent.

Reading the participation numbers. Kenya (64 percent) and Ghana (60 percent) show the deepest football-betting bases, followed by Tanzania (59 percent), South Africa (58 percent), Uganda (57 percent), and Nigeria (54 percent). More than half of adults in each of these markets bet in the past year, which is a large and mainstream audience.
The rest of the findings in this report are based on people who have placed a bet in the past, so the sections that follow describe the behavior of active bettors
What people bet on
Football is the dominant product overall, named by 67 percent of bettors as what they play most often. Aviator and other crash-style games follow at 13 percent, casino games at 11 percent, and lotteries at 5 percent.

The regional average hides the sharpest divide in the study. Football leads in five markets, reaching 84 percent of bettors in Uganda, 81 percent in Nigeria, and 78 percent in Tanzania. South Africa is the exception: football reaches only 29 percent there, while casino games lead at 36 percent and lotteries draw 16 percent, both far above any other market. Kenya stands out separately for Aviator at 24 percent, roughly double the next-highest market. This mirrors a wider trend: game provider Spribe reports Aviator player numbers in Africa grew about 54 percent year on year, as lightweight crash games win share from traditional sports betting.

South Africa’s product mix reflects the region’s most developed and tightly regulated gambling market. The country’s National Gambling Board reports that online betting now generates about 60 percent of national gambling revenue, and Statistics South Africa has documented a rising national appetite for gambling and betting. The wider range of casino and lottery products available to South African bettors helps explain why their preferences look so different from those in the football-led markets to the north.
How often people bet
Betting is frequent, and the pattern is consistent across the region. Once a week is the single most common answer. Overall, 55 percent of bettors play at least weekly, and 28 percent play once a day or more. Country-level frequency varies only slightly, so this is best read as a regional constant: this is a high-frequency category, not an occasional one.

The mobile channel is universal
There is almost no variation by channel. Across all markets, 95 percent of bettors place bets on a mobile device, ranging narrowly from 94 percent in Uganda to 96 percent in Kenya, Ghana, Nigeria, and South Africa. Mobile is not a growing channel here, it is effectively the only channel. Mobile experience, data cost, and app or web performance are the real competitive battleground rather than a secondary consideration.
How much people spend
Monthly betting spend is modest for most bettors and concentrated at the low end. Overall, 58 percent spend under 10 US dollars a month and another 24 percent spend between 10 and 25 dollars. Only about 10 percent spend 50 dollars or more.

Spend is where Uganda separates from the rest. Only 35 percent of Ugandan bettors spend under 10 dollars, 40 percent fall in the 10 to 25 dollar band, and 6 percent report spending above 500 dollars a month, the highest high-spender share in the region. South Africa also skews higher, with 11 percent spending 50 dollars or more. Tanzania is the most value-conscious market, with 67 percent under 10 dollars.

Who is betting
The betting audience skews young. The 25 to 34 age group is the largest segment overall at 45 percent, followed by 18 to 24 at 26 percent and 35 to 44 at 23 percent. Older bettors are a small minority.

Age tilts by market are worth noting. Uganda is the youngest-concentrated, with 59 percent of respondents aged 25 to 34. Kenya has the strongest 18 to 24 presence at 36 percent. South Africa is the oldest, with 38 percent aged 35 to 44 and 11 percent aged 45 to 54, the highest older share in the study.
Gender is the sharpest demographic contrast. Overall, 69 percent of respondents are male. Betting audiences are heavily male in Ghana (82 percent), Tanzania (78 percent), Uganda (76 percent), and Nigeria (73 percent), more balanced in Kenya (61 percent male), and reversed in South Africa, where women make up 54 percent, the only market where female bettors are the majority.

What it means for the market
- Treat each market separately. A single continental strategy misreads the region. South Africa’s casino and lottery lean, Kenya’s crash-game appetite, and Uganda’s higher spend each call for distinct product and marketing approaches.
- Football is the acquisition anchor, except in South Africa. In five markets, football is the entry product and the natural focus for sponsorships and odds-led marketing. In South Africa, casino content and lotteries deserve top billing.
- Compete on mobile experience. With 95 percent of bettors on mobile everywhere, load speed, data efficiency, and app reliability are the real differentiators.
- Plan for high frequency. Weekly and daily play is the norm, so retention, live betting, and responsible-play controls matter as much as acquisition.
- Segment by value. Most bettors are low spenders, but Uganda and South Africa carry meaningfully larger high-spend tails worth targeting with tailored offers.
Methodology and notes. GeoPoll surveyed 2,866 respondents across Ghana (547), Kenya (557), Nigeria (526), South Africa (496), Tanzania (428), and Uganda (312) between 24 June and 16 July 2026, using GeoPoll’s mobile survey channels including SMS, WhatsApp, and the GeoPoll app. Participation figures reflect the share of respondents who reported placing a bet on football in the past 12 months. Product, frequency, channel, and spend figures describe active bettors. Spend bands were collected in local currencies and converted to comparable US dollar ranges. Percentages are rounded to the nearest whole number and may not sum to exactly 100. Figures describe the survey audiences and are not adjusted to full national population estimates. This is a rapid dipstick survey following a natural fallout, without strict quotas. This is a rapid dipstick survey following a natural fallout, without strict quotas. To conduct a scientific study on gambling or other topics in Africa, Asia, and Latin America, please contact GeoPoll.
The post Research Report: Betting in Africa 2026 appeared first on GeoPoll.
]]>The post Venezuela Earthquake: Dispathes from Inside the Disaster Zone #2 appeared first on GeoPoll.
]]>This report updates our first assessment, published on 28 June. The larger sample widens geographic coverage across the country and lets us separate the areas in crisis from those that felt only a tremor with far greater confidence.
Summary Findings
- The impact is concentrated, and the pattern held as the sample grew. Six states along the central coast and capital corridor account for 432 of 846 responses. La Guaira (average felt intensity 9.6 out of 10), Caracas (8.8), Miranda (8.4), Carabobo (8.3) and Aragua (8.3) remain the core of the disaster. Yaracuy (7.4) emerged as a newly prominent high-intensity state in the larger sample.
- Quake-driven needs cluster sharply in the impact zone. Housing damage, displacement, loss of drinking water, blocked roads and compromised hospitals are two to three times more common inside the zone than outside it.
- Food, power and connectivity gaps appear nationwide. Limited food (51 percent in the zone, 45 percent outside), unreliable electricity and patchy connectivity are elevated everywhere, pointing to pre-existing strain the earthquake compounds rather than causes. Distinguishing the two matters for targeting.
- Water and food are the binding constraints in the zone. 41 percent of impact-zone households report limited or no drinking water and 51 percent limited or no food. Food was the single most requested need in open responses, named by roughly 293 households nationwide.
- Displacement is real but a minority. In the impact zone, 81 households (19 percent) will not sleep in their own home, including 17 sleeping outdoors or in the street.
- The information gap persists. Nationwide, 58 percent said the information they most need but cannot get is aftershock and safety updates, and nearly four in five rely on social media or WhatsApp for earthquake information.
- Respondents skew older and urban. The mean respondent age is 53 and 59 percent live in urban areas. This shapes interpretation and is discussed in the methodology note.
Background and method
The emergency
The 24 June sequence was felt most violently along the north-central coast and in Caracas. Authorities declared La Guaira a disaster zone and reported that more than 70,000 families were affected. Official casualty figures, which remain the authoritative source for loss of life, ranged as of late June from roughly 188 to 235 dead and more than 4,300 injured, with numbers expected to rise as assessment continued.
GeoPoll fielded a rapid needs assessment via WhatsApp, reaching people on the phones already in their hands and allowing them to report their own conditions. The instrument covers 54 questions spanning location, felt intensity, household casualties, housing, displacement, water, food, power, connectivity, roads, hospital access, gas and fire risk, information needs and sources, and demographics.
Finding 1: The impact is geographically concentrated
When we map self-reported shaking intensity by state, a clear cluster emerges along the north-central coast and capital corridor, matching the areas authorities and humanitarian agencies identified as worst affected. We define the impact zone as six states, consistent with our first report, so the two rounds can be compared directly.

The six-state impact zone accounts for 432 of 846 responses, roughly 51 percent of the sample. La Guaira, which residents rated the most severe, is where authorities declared a disaster zone. The independent, household-level data points to the same epicenter of suffering that official channels identified, which raises confidence in both.
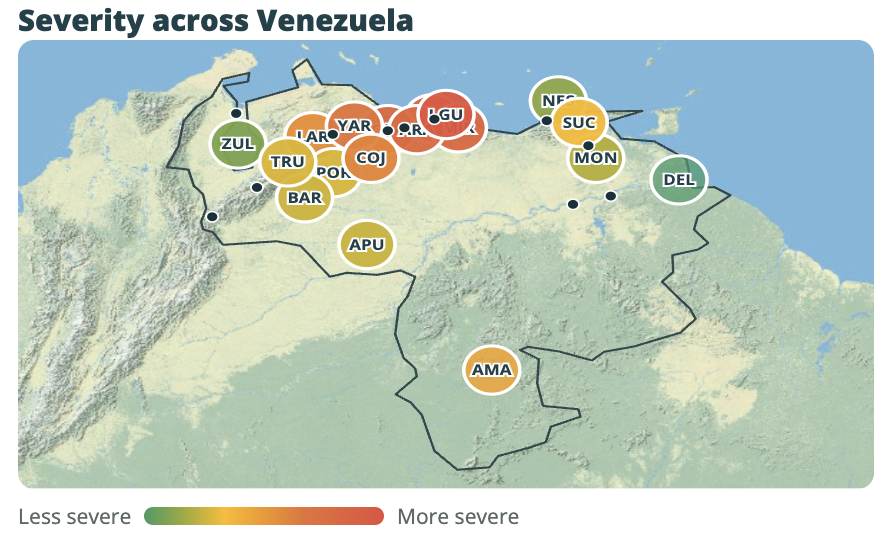
The contrast at the bottom of the chart is the actionable part. Need is concentrated, not diffuse. Resources directed to the central coast and capital region will reach the people in crisis. Broad national distribution would spread thin across areas that report little damage.
Finding 2: Inside the impact zone, what households face
The larger sample allows a comparison the first report could not make cleanly: conditions inside the impact zone against a substantial rest-of-country sample. That comparison separates the needs the earthquake created from the strain Venezuelan households were already living with. Both are real. They call for different responses.

Quake-driven: housing, displacement, water and access
Inside the impact zone, 60 percent of households report home damage, including 28 with major damage, unsafe conditions or a home destroyed. Across the rest of the country combined, only 9 households reported major damage or destruction. Displacement follows the same line: 81 impact-zone households (19 percent) will not sleep in their own home, of whom 52 are staying with relatives or neighbors and 17 are sleeping outdoors or in the street, mirroring what responders report in Caracas and La Guaira, where residents fear weakened buildings could collapse in an aftershock.
Water shows the same quake signature. In the impact zone, 31 households report no drinking water and 146 only limited water, 41 percent constrained against 23 percent outside the zone. Caracas alone accounts for 15 households with no water and 53 with limited supply. Blocked roads and damaged or unreachable hospitals also concentrate in the zone, at 40 and 38 households respectively.
Nationwide strain: food, power, connectivity
Food scarcity is worst in the zone (51 percent limited or none) but high everywhere (45 percent outside), and electricity problems are actually more common outside the zone (38 percent against 30 percent), led by chronically affected states such as Zulia. These are largely pre-existing national conditions the earthquake compounds locally. Zone targeting addresses the quake damage; only broader programming addresses the baseline strain.
Finding 3: The human toll, in the words of those reporting it
Each figure below is a household that reached out. These are counts of respondents reporting an emergency in their own household, not population totals. Trapped-person reports concentrate almost entirely in the impact zone: 25 of the 28 come from inside it.

Some households also reported a death in the family. Consistent with the principle stated in the graphic, we do not publish a casualty count and defer to official figures. These reports do, however, signal where bereavement support and family tracing are most needed, concentrated in the impact zone.
Behind each figure is a voice. Respondents were asked, in one or two words, what their household needs most. Their answers, published anonymously and without editing, carry the assessment better than any aggregate.
“Que los saquen de los escombros, necesitamos maquinarias y voluntarios”Caracas; home destroyed, family in La Guaira, relatives missing
“Mi hijo es militar y está en La Guaira y no me he comunicado con él desde las 11 de la mañana”Caracas
“Agua potable y comida con urgencia”La Guaira; household displaced, no water
“Que aparezca mi hermano”Trujillo; family member missing
“Enlatados, agua, pasta de dientes, jabón, bombillos recargables, velas”La Guaira; sheltering, home damaged
“Ayuda psicológica y comida”Miranda
Many respondents whose own homes were intact used the same open text to point responders elsewhere, writing that others nearby had lost more. That instinct is worth noting for coordination: community members are themselves flagging where the deepest need sits.
Finding 4: The information environment and what people cannot find out
Disruptions to power and telecommunications, in an already limited information environment, have made it hard for residents and their relatives to learn what has happened. The assessment measured both what information households most need and where they are getting it.

Aftershock and safety information dominates every other need by a wide margin, inside and outside the impact zone alike. People are not only short on water and shelter, they are short on the knowledge they need to decide whether to sleep inside, when to return, and how to stay safe if the ground shakes again.
The channel data explains why the gap persists and what to do about it. Households rely overwhelmingly on informal digital channels rather than official broadcasts. If nearly four in five people get earthquake information from social media and WhatsApp, then official aftershock guidance, return-safety advice and shelter information will reach them fastest through those same channels. A WhatsApp assessment like this one is not only a listening tool. It is a demonstrated delivery channel for the exact safety information households say they cannot get.
Finding 5: What people say they need most
Beyond the structured indicators, households described their most pressing need in their own words. Coding those open responses into themes gives a demand-side view of priorities that closed questions cannot.

Three points stand out for responders. First, food has overtaken water as the most frequently named need in this larger sample, though both remain acute and often appear together in the same response. Second, psychological support recurs often and explicitly, with dozens of households asking for calm, reassurance or mental health help, an easily overlooked need in the first days after a quake. Third, many households frame their need economically, asking for the means to buy food and materials rather than the items themselves, which is relevant to any cash-based response design
Implications for the response
The assessment points to a clear, sector-linked set of priorities for the central coast and capital region.
- Target geographically. Concentrate water, shelter and repair response on La Guaira, Caracas, Miranda, Carabobo, Aragua and Yaracuy. The data does not support thin national distribution for quake-driven needs.
- Lead with water and food. Roughly half of impact-zone households report constrained food and four in ten constrained water. These are the binding daily constraints and the top open-text asks.
- Distinguish quake damage from chronic strain. Housing, displacement, water and access problems are quake-specific and zone-targeted. Food, power and connectivity gaps are national; programming for them should not assume they end at the zone boundary.
- Design for cash where markets function. Many households ask for the means to buy essentials, suggesting cash or voucher modalities can work alongside in-kind distribution.
- Resource medical outreach and family tracing in the zone. Trapped-person, injury, missing-person and damaged-hospital reports cluster almost entirely in the impact zone.
- Include mental health and psychosocial support. Requests for calm and psychological help are frequent and explicit.
- Deliver safety information through social media and WhatsApp. That is where nearly four in five households already get earthquake information, and aftershock and return-safety guidance is the single most requested unmet need.
Data access and how GeoPoll can help
GeoPoll specializes in reaching people that other data collection methods miss, gathering direct household input from hard-to-reach and crisis-affected populations across emerging markets, fast. This assessment was fielded over WhatsApp and reached hundreds of households within hours of launch.
We are sharing this assessment and the live dashboard openly with the relief and aid community. The dashboard lets responders filter by state and explore each indicator in detail, and it continues to update as more responses arrive. The full dataset can be broken down by state, municipality, indicator or population group to match what a given response requires. GeoPoll can also field follow-up questions to the same households or launch a new rapid assessment within hours.
- Live dashboard: surveys.geopoll.com/art/venezuela-earthquake
- First report: geopoll.com/blog/venezuela-earthquake-report
- Contact: geopoll.com/contact-us
Methodology note
Mode: WhatsApp self-completion survey. Field period: 25 June to 11 July 2026, ongoing. Completed responses in this report: 846. Instrument: 54 questions in Spanish covering location, felt intensity, household casualties, housing, displacement, water, food, power, connectivity, roads, hospital access, gas and fire risk, information needs and sources, and demographics.
Analysis: Figures are unweighted counts and percentages of respondents. Felt intensity is self-reported on a 1 to 10 scale; 833 of 846 respondents gave a numeric rating. The impact zone comprises La Guaira, Capital District (Caracas), Carabobo, Miranda, Aragua and Guárico, defined for consistency with the first report. Urgent-medical need was asked only of households reporting an injury. A small number of open-ended fields were coded into themes for the needs analysis. All charts in this report are generated directly from the response data.
Limitations: The sample is self-selected and opt-in, unweighted, skews older and urban, and broadened in composition as outreach expanded. Households in the worst-hit areas without power, signal or a working phone are underrepresented, so severe conditions are more likely understated than overstated. These data complement, and do not replace, official damage and casualty figures.
Ethics: Responses were collected anonymously. Quotes are published without identifying information. GeoPoll does not publish its own casualty figures and defers to official sources for loss of life. GeoPoll participates in IRB processes and is a member of ESOMAR, WAPOR, PAMRO and the Society for International Development.
The post Venezuela Earthquake: Dispathes from Inside the Disaster Zone #2 appeared first on GeoPoll.
]]>The post A decade on the front line: what mobile data has taught us about responding to Ebola and other outbreaks appeared first on GeoPoll.
]]>On 15 May 2026, the Democratic Republic of the Congo declared its 17th Ebola outbreak. Within 48 hours, the World Health Organization declared a Public Health Emergency of International Concern. As of late May, more than 1,200 suspected and confirmed cases had been reported with over 260 deaths. The outbreak is caused by Bundibugyo virus, a rare Ebola strain for which no approved vaccine yet exists. Imported cases have been confirmed in Uganda, Germany, and the Czech Republic.
For GeoPoll, the news triggered an immediate question that has driven our work for the past twelve years: how do we collect reliable, representative data from communities that field teams cannot safely or easily reach, fast enough to inform a live response.
This article walks through GeoPoll’s published experience supporting responses to Ebola, COVID-19, cholera, and Mpox across Africa and Asia, and lays out what we offer partners now.
Where it began: West Africa, 2014
The 2014 to 2016 West Africa Ebola outbreak killed nearly 12,000 people across Guinea, Liberia, and Sierra Leone. It also became the moment that mobile data collection in humanitarian crises moved from promising idea to operational reality.
When the outbreak peaked, GeoPoll was finalising its SMS survey system in Liberia. As we documented in the Journal of Health Communication, that timing meant we could begin running surveys immediately. We did not have to build infrastructure from scratch in the middle of a crisis. The same is true today. Our platform, panel, and mobile network operator integrations are in place in the affected countries before the next outbreak begins.
What we did across the West Africa outbreak
In the years that followed, our SMS and CATI surveys in Liberia, Sierra Leone, and Guinea covered a range of programme questions. Several of these projects are documented in published case studies and peer-reviewed work:
- Food security tracking with the United Nations World Food Programme. Over three months in Sierra Leone, Liberia, and Guinea, we collected indicators on food prices, wages, and household coping. The work adapted the reduced Coping Strategies Index for mobile delivery, with prior validation showing no significant difference between mobile and face-to-face collection. Case study.
- Market functionality monitoring for the Famine Early Warning Systems Network. Panel-based SMS surveys with market traders in Sierra Leone and Liberia, tracking market sizes, operating costs, stock levels, and agricultural activity through ten rounds. Case study.
- Long-term economic impact surveys for the USAID Bureau for Africa and FHI360. Thirteen rounds of nationally stratified surveys in Liberia and Sierra Leone between January and June 2015, tracking income, employment, food prices, and schooling. Sample base of 1.8 million in Sierra Leone and 1.6 million in Liberia, with 1,000 completes per country per round. Case study.
- Health communications research with Johns Hopkins University in Liberia. SMS-based community dialogue and rumour tracking, supporting Ebola risk communication and community engagement. Documented in the academic literature.
- Community perceptions in Sierra Leone with Keystone Accountability. Assessing how the population viewed the international community’s response in real time.
Across the West Africa outbreak, GeoPoll reached more than 100,000 people. The methods worked because the people we surveyed already had access to mobile phones, our network operator integrations meant respondents incurred no cost to participate, and the SMS and voice modes did not require enumerators to enter quarantine zones or treatment areas.
What we learned
Three operational lessons from 2014 to 2016 still shape how we run surveys during outbreaks today:
- Keep surveys short. On SMS, response rates drop sharply beyond 12 to 15 questions. The constraint forces discipline on what we ask.
- Pre-code open-ended questions. 160-character limits and noisy environments mean structured response options outperform free text for most use cases.
- Always offer airtime credit on completion. Small incentives (we have typically used the local equivalent of about USD 0.50) significantly improve completion rates among low-income respondents.
Beyond West Africa: outbreaks in the DRC and the eastern corridor
Between 2018 and 2020, the DRC experienced two more large Ebola outbreaks in the eastern part of the country, primarily in North Kivu and Ituri. GeoPoll deployed mobile surveys during these outbreaks as well, focused on socio-economic impact and information flow. By the time we entered the COVID-19 era in 2020, we had effectively built a playbook for outbreak response work and applied it across an expanding set of geographies and health threats.
Our experience now spans the major health emergencies of the last decade:
- Ebola: Liberia, Sierra Leone, Guinea (2014 to 2016) and the DRC (2018 to 2020)
- COVID-19: 30+ countries across sub-Saharan Africa, the Middle East and North Africa, and Asia
- Cholera: Zambia (2024) and other African geographies
- Mpox: DRC, Burundi, Rwanda, Uganda, Central African Republic, and Kenya (2024)
- Other infectious disease and vaccine work: malaria, polio, measles, yellow fever, and routine immunisation studies across multiple African countries
COVID-19: when the playbook scaled
When COVID-19 reached sub-Saharan Africa in 2020, the methods we had refined for Ebola scaled up overnight. Between 2020 and 2022, GeoPoll ran self-funded and partner-funded research across more than 30 countries, covering economic impact, food security, vaccine acceptance, and risk communication. Findings from our November 2020 vaccine acceptance study across Cote d’Ivoire, the DRC, Kenya, Mozambique, Nigeria, and South Africa were archived publicly in ICPSR and used by researchers and policy makers globally.
We continued tracking vaccine perceptions across multiple rounds. The April 2021 follow-up, reported on the GeoPoll blog, found that fewer than half of respondents (48 percent) felt they had been given enough trustworthy information about the vaccine, a finding that mirrored what we were seeing on the ground.
The COVID work cemented two principles we now apply by default in outbreak research:
- Multi-mode is non-negotiable. SMS reaches the broadest base but limits depth. CATI handles longer instruments and complex skip logic. Mobile web reaches smartphone-heavy segments. In-person fills gaps for offline populations. The best outbreak studies combine modes by design, not as a fallback.
- Trust matters more than reach. A representative sample of people who refuse to answer honestly is not a sample. We invest in respondent identity verification, plain-language consent, and call-centre training in local languages because trust at the moment of the interview drives data quality.
Mpox: turning prior experience into rapid mobilisation
When mpox began spreading through Central and Eastern Africa in 2024, GeoPoll moved into the response within weeks. As we wrote at the time, the parallels with earlier outbreaks were clear: a disease moving faster than traditional surveillance, vaccine hesitancy reshaping its trajectory, and demand from public health partners and pharmaceutical companies for granular, real-time data.
Through late 2024 we ran mpox vaccine acceptance and behaviour monitoring rounds across six African countries: DRC, Burundi, Rwanda, Uganda, Central African Republic, and Kenya. The DRC mpox vaccine acceptance work has since been published in peer-reviewed medical literature and remains one of the largest mobile-based mpox studies on record from that period.
Cholera Zambia: a public-good data drop in the middle of a crisis
In early 2024, while Zambia was managing a cholera outbreak that had infected more than 21,000 people and caused over 700 deaths, GeoPoll ran a self-funded nationwide CATI survey to understand public awareness, water and sanitation access, and behaviour change. The findings were released as a public report on ReliefWeb with an interactive dashboard. The study used a stratified random sample of 400 respondents drawn from our Zambia panel, delivered in English, Bemba, and Nyanja from our Lusaka call centre.
The point of that work was not commercial. It was to demonstrate something that we believe matters more than any single study: in a crisis, the right response is to gather and share data quickly, even when there is no client paying for it.
What we offer partners responding to the 2026 outbreak
The capability that an organisation needs during an outbreak is not abstract. It is a short list of practical things, done quickly and well. Here is what we offer.
Mobile data collection across multiple modes
We run surveys through the channels respondents actually use. Most outbreak studies blend these by design:
- SMS surveys: Free-to-user via mobile network operator integrations. Best for broad reach, short instruments, and reaching low-income or rural populations. Used heavily in our Ebola, COVID, and cholera work.
- Computer Assisted Telephone Interviewing (CATI): Live calls from our call centres in Nairobi, Lusaka, Dar es Salaam, Johannesburg, and Panama City. Best for longer instruments, complex skip logic, sensitive topics, and qualitative depth.
- Mobile web (link-based): Surveys delivered via WhatsApp, SMS link, or other distribution. Best for smartphone-heavy segments, image-based questions, and longer self-completion.
- GeoPoll App: Our smartphone application supports longer panels and incentivised tracking studies.
- In-person interviewing: Where offline populations or sensitive observations are needed, we deploy trained field teams. Used selectively in our outbreak work, primarily for qualitative and validation purposes.
Reach across affected geographies
GeoPoll has more than 5 million profiled panelists and access to over 250 million individuals across 64 countries. In the geographies most relevant to the current Ebola outbreak, our panel and infrastructure are operational today:
- Democratic Republic of the Congo: active panel and call-centre capacity. French, Lingala, Kiswahili, and Kinande supported.
- Uganda: active panel, English and major local languages.
- Adjacent at-risk countries: Rwanda, Burundi, Tanzania, South Sudan, Central African Republic, and Kenya all have operational panels.
Speed when speed matters
Outbreak response cannot wait three months for fieldwork. Typical timelines for GeoPoll outbreak studies:
| Activity | SMS / mobile web | CATI |
| Questionnaire design and review | 2 to 3 days | 2 to 3 days |
| Translation and localisation | 1 to 2 days | 1 to 2 days |
| Pilot and adjustment | 1 to 2 days | 1 to 2 days |
| Full field period | 2 to 5 days | 5 to 10 days |
| Initial findings | 1 to 2 days after field | 2 to 3 days after field |
| Total from kickoff to insight | 1 to 2 weeks | 2 to 3 weeks |
Methodology that holds up to scrutiny
Outbreak research is read by epidemiologists, donors, and ethics committees. Our default methodology is designed to pass that scrutiny:
- CDC-aligned KAP frameworks. We design knowledge, attitudes, and practice instruments to be compatible with established disease-response frameworks.
- Stratified random sampling. By gender, age, and geography. We report margins of error and confidence intervals consistently.
- IRB experience. We have participated in institutional review board processes with universities and research partners. Our research follows ESOMAR and WAPOR ethical standards.
- Transparent reporting. Every study reports its sample size, margin of error, languages, mode, and field period. We do not hide methodology.
Senselytic for real-time qualitative analysis
Outbreaks generate a lot of qualitative signal: open-ended responses, call-centre notes, social listening, focus group transcripts. Senselytic, our AI-powered qualitative analysis tool, helps partners extract patterns from this material in hours instead of weeks. We used it to support analysis on multi-country COVID and mpox studies, and it is a core capability for the current Ebola response.
Two ways partners can engage with us
For the current Bundibugyo outbreak, we are offering two complementary engagement options. They can stand alone or run in parallel:
1. Commissioned research
Bespoke studies designed around a single partner’s questions. Suitable when you have specific decision needs, geographic priorities, or contractual reporting requirements. Examples we are equipped to run today include vaccine acceptance and intent, risk communication effectiveness, healthcare-seeking behaviour, rumour and misinformation surveillance, food security and economic impact in affected zones, and case investigation support.
2. Ebola Outbreak Omnibus Survey
A shared, nationally representative DRC survey where multiple organisations contribute custom questions and receive their own answers plus common themes. Costs are shared, fielding is faster, and results are comparable across participating organisations. Suitable for partners who need data but do not require a full standalone study. A parallel Uganda omnibus will run if there is sufficient interest.
| Specification | DRC Omnibus |
| Sample size | 1,000 completes, nationally representative |
| Margin of error | Approximately 3.1% at 95% confidence |
| Modes | Smartphone and WhatsApp lead, SMS and CATI fall back |
| Languages | French and Lingala lead, Kiswahili and Kinande added in eastern provinces |
| Field period | 7 to 10 days |
| Custom questions per partner | Configurable, typically 5 to 10 |
| Cost model | Shared across participants, per-question pricing |
Get in Touch
Bundibugyo Ebola has no approved vaccine. The response will succeed or fail on case finding, contact tracing, risk communication, and community trust. All four depend on understanding what people in affected areas actually believe, know, fear, and need. That understanding cannot be assumed and it cannot be sampled from clinic registers alone. It has to be collected from people, in their own language, on a platform they already use.
GeoPoll has been collecting that kind of data through every major African outbreak of the last twelve years. The infrastructure is in place. The methodology is documented. The team is mobilised. We are ready to support partners working on this response, from public-good monitoring to bespoke programme evaluation, from rapid omnibus participation to long-term tracking studies.
In every outbreak we have worked on, the lesson has been the same: speed compounds. Decisions made on Day 7 with imperfect data are usually better than decisions made on Day 30 with perfect data. We are built to deliver on Day 7.
To learn more, discuss commissioned research, or to participate in the Ebola Outbreak Omnibus Survey, contact us.
The post A decade on the front line: what mobile data has taught us about responding to Ebola and other outbreaks appeared first on GeoPoll.
]]>The post What is AI Enumeration? A Practitioner’s Guide to AI-Led Survey Interviews appeared first on GeoPoll.
]]>The term borrows from traditional survey research, where “enumeration” refers to the act of collecting data from respondents in the field, by phone, or through mobile channels. AI enumeration applies the same function to a new mode of delivery.
For research teams operating at scale across multiple languages and time zones, AI enumeration is one of the most significant methodological shifts since the move from face-to-face interviewing to computer-assisted telephone interviewing (CATI). But like any new method, it works well in some contexts and poorly in others, and understanding the difference is what separates useful adoption from expensive experimentation.
This guide covers what AI enumeration is, how it works, where it adds value, where it falls short, and why research expertise and verified respondent panels remain essential even as the interview itself becomes automated.
How AI enumeration works
At a mechanical level, AI enumeration systems combine three technologies: speech recognition to understand what the respondent says, a large language model to interpret meaning and generate follow-up questions, and text-to-speech to deliver questions in a natural voice.
The AI follows a structured questionnaire, just as a CATI interviewer would, but it can adapt within defined boundaries. If a respondent gives an unclear answer to an open-ended question, the AI can probe for clarification. If a respondent mentions something worth exploring, the AI can branch into a follow-up. And if the respondent speaks a different dialect or code-switches between languages, modern systems can often keep up.
The respondent experience varies. Some AI enumeration deployments use voice over the phone, mirroring traditional CATI. Others use voice through WhatsApp or messaging apps. A few use text-based chat interfaces. The common thread is that the interview feels like a conversation rather than a form.
AI enumeration versus traditional enumeration
Traditional enumeration relies on trained human interviewers. It is proven, flexible, and capable of handling almost any research context, but it is also expensive, slow to scale, and subject to variability between interviewers.
AI enumeration flips several of these tradeoffs. It scales almost instantly, runs consistently across thousands of interviews, and operates in any language the model supports, at any hour, without fatigue. What it gives up, at least for now, is the human judgment that skilled enumerators bring to difficult interviews: reading hesitation, building rapport with reluctant respondents, and knowing when to push and when to step back.
Neither method is universally better. The useful question is which method fits which study, and for many projects the answer is a thoughtful combination of both.
Advantages of AI enumeration
- Cost efficiency at scale. Human enumeration costs scale roughly linearly with sample size. AI enumeration has a higher fixed setup cost but much lower marginal cost per interview, which makes it economical for large samples, tracking studies, and high-frequency research. A study that would require hundreds of call center hours can often be completed in a fraction of the time at a fraction of the cost.
- Speed to field and speed to data. An AI enumerator can start interviews as soon as the questionnaire is approved and the sample is ready. There is no enumerator training, no briefing, no staffing up for peak periods. Fielding windows that used to take two to three weeks can close in days, and because the AI transcribes and codes as it goes, clean data is available almost immediately after the last interview completes.
- Consistency across interviews. Every respondent hears the same question in the same tone with the same phrasing. Interviewer effects, which are a real and often underdiscussed source of measurement error, are largely eliminated. This matters especially for tracking studies, where even small shifts in enumerator behavior between waves can create noise and bias that look like signals.
- Language and dialect coverage. Multilingual studies have traditionally required recruiting, training, and managing enumerators in each language. AI systems trained on sufficiently large speech datasets can handle dozens of languages, including low-resource languages that are difficult to staff for. This is a particularly meaningful advantage in regions like Sub-Saharan Africa, where a single national study might need to run in five or more languages.
- Respondent candor on sensitive topics. There is a growing body of evidence that respondents disclose more openly to AI interviewers on sensitive subjects, including health behaviors, financial status, political attitudes, and experiences of discrimination or violence. The absence of social judgment seems to reduce the performative element of responses that skews sensitive-topic data.
- 24/7 availability. AI enumerators do not have shifts. Respondents in rural areas who are only reachable in the evening, or business owners who can only talk after closing, can be interviewed whenever they are available. This expands the reachable universe and reduces the bias introduced by sampling only people who answer during call center hours.
- Scalability without quality degradation. In traditional enumeration, scaling a study often means hiring less experienced interviewers, which degrades quality at exactly the moment you need it most. AI enumeration holds quality constant regardless of sample size.
Drawbacks and considerations
- Rapport limits. Human enumerators build trust through small cues: warmth, acknowledgment, cultural references, shared language. AI systems are getting better at this, but they still struggle with the kind of rapport that gets a reluctant respondent to open up or a busy executive to stay on the line. For studies where participation depends on rapport, human enumeration is still the better choice.
- Complex probing and narrative elicitation. AI enumerators can probe effectively on structured open-ends, but they might fall short in deep narrative elicitation, especially when not well trained, where the interviewer needs to follow an unexpected thread, understand implicit meaning, or recognize when a respondent is circling back to something they have not yet said. Ethnographic and deeply qualitative work remains firmly in human territory.
- Respondent trust and consent. Respondents have a right to know they are speaking with an AI. Disclosure is both an ethical and, increasingly, a regulatory requirement. Studies need to handle this transparently without suppressing participation.
- Data security and model choice. AI enumeration involves sending the respondent’s speech to speech recognition and language models. The choice of models, where they are hosted, and how respondent data flows through the system are all material questions, particularly for studies involving vulnerable populations or regulated data.
Why research expertise still matters
AI enumeration automates the interview. It does not automate research.
Designing a study that yields valid, useful insights still requires methodological judgment: framing the research question, selecting the appropriate methodology, designing a questionnaire that avoids leading and double-barreled items, setting quotas that reflect population realities, defining weighting schemes that correct for known sample biases, and interpreting results in context. None of this is done by the AI.
If the questionnaire is poorly designed, an AI enumerator will execute it flawlessly and produce flawless garbage. If the sampling frame is biased, running the interviews through AI will produce precise estimates of the wrong quantity.
To get value from AI enumeration, researchers must pair it with genuine research expertise. If you treat AI enumeration as a replacement for research thinking, you will ship studies faster and be wrong faster.
Why a respondent database still matters
The second thing AI enumeration does not solve is the sample.
An AI enumerator needs someone to interview. That means a reachable, representative, profiled, and willing respondent base. Building such a base takes years and requires serious investment in recruitment, verification, profiling, re-engagement, and incentive management. It is not commodity infrastructure, and it cannot be conjured at the moment a study is commissioned.
In regions where traditional sampling frames are incomplete and where reaching specific demographic segments requires deliberate panel construction, the quality of the underlying respondent database largely determines the quality of any study run on top of it. An AI interviewer that calls the wrong people efficiently is not useful.
This is the pattern likely to play out across the industry: AI enumeration will become widely available, but the research buyers who get meaningful results will be the ones working with providers who own and actively maintain the respondent relationships the interviews depend on.
This is where organizations like GeoPoll, which has access to over 300 million mobile subscribers, come in. To provide a diverse enough sample to produce good research.
Best practices for AI-enumerated studies
- Pilot before you scale. Always run a pilot of at least 50 to 100 interviews before a full rollout. Listen to the recordings. Check the transcriptions. Identify the questions where respondents are confused, the probes that are not firing, and the moments where the AI misinterprets an answer. Fix before scaling.
- Design questionnaires for voice. Questionnaires that work on self-complete mobile surveys do not always work for voice. Long question stems, complex scales, and nested skip patterns that are fine for a human enumerator can confuse both the AI and the respondent. Shorter, cleaner, more conversational phrasing produces better results.
- Plan QA before fielding, not after. Decide in advance what proportion of interviews will be reviewed, what flags will trigger review, and who owns the review process. Budget time and cost for it.
- Use hybrid designs deliberately. AI for the scalable, structured portion of the study; human enumerators for the harder segments (rural, elderly, sensitive follow-ups, and qualitative deep dives). The best hybrid designs are intentional about which mode handles which respondent type.
- Be transparent with respondents. Disclose at the start that the interview is being conducted by an AI. Give respondents the option to decline. Respondents who participate under clear consent give more reliable data than those who feel tricked.
- Measure mode effects. If you are transitioning a tracking study from human CATI to AI enumeration, run a bridge study. Mode effects are real and measurable, and pretending they do not exist is how tracking data quietly loses its comparability.
Use cases for AI enumeration
- Large-scale tracking studies. Brand health, political opinion, consumer confidence, and public health tracking studies all benefit from AI enumeration’s consistency and cost efficiency, particularly when they run monthly or quarterly across multiple markets.
- Multilingual research in emerging markets. Studies that span multiple countries or multiple languages within a country, including African markets where staffing enumerators across five or more languages is a recurring operational challenge, can be run more cheaply and consistently with AI enumeration.
- Rapid-turnaround studies. Crisis response research, reaction studies around news events, and tight-deadline commercial studies all benefit from the speed advantages of AI fielding.
- Sensitive-topic research. Studies on health behaviors, financial vulnerability, gender-based violence, and political attitudes can produce more candid data through AI enumeration, though with strong ethical guardrails and clear pathways to human support where relevant.
- Panel recontact and longitudinal work. Reaching existing panel members for follow-up waves is operationally expensive with human enumerators. AI enumeration lowers the cost enough to make more frequent, lighter-touch recontact viable.
- Hard-to-reach schedules. Research with business owners, healthcare workers, farmers during harvest, or parents with young children requires flexibility that fixed call center hours cannot easily provide. AI enumeration’s always-on availability changes what is reachable.
Where AI enumeration is headed
AI enumeration will not replace human enumerators across the board. It will be for specific kinds of work, at specific scales, in specific contexts, while expanding the total volume of research that is economically viable. Integrating AI enumeration into a broader research offering rather than treating it as a standalone product is the current stance.
Powered by the ASR models we have been creating over the last few years using GeoPoll AI Data Streams, GeoPoll is currently running AI enumeration across our own survey platform. Our focus on multilingual performance in Africa, Asia, and Latin America, and on the quality controls that make AI-collected data fit for client use.
If you are thinking about AI enumeration for your research project, or if you would like to discuss a pilot, get in touch with the GeoPoll team.
The post What is AI Enumeration? A Practitioner’s Guide to AI-Led Survey Interviews appeared first on GeoPoll.
]]>The post The Top TV and Radio Stations in Tanzania – Q1 2026 appeared first on GeoPoll.
]]>Broadcast television and radio remain central to daily life in Tanzania, with the market shaped by distinctive features: a powerful sports-led TV ecosystem, a single evening peak that dwarfs every other viewing window, and a radio dial where three stations account for most of the national listening share.
GeoPoll’s Audience Measurement (GAM) data from January to March 2026 provides a picture of who is watching, who is listening, and when. This report distills the Q1 2026 numbers into the trends that matter for broadcasters, advertisers, and media planners operating in Tanzania.
As you read through this overview, remember that this is a high-level summary of national reach and share for Q1 2026. Weekly and monthly shifts, regional breakdowns, content-level performance, advertising effectiveness studies, and hourly unique-audience analysis are not covered here. For deeper insights, please reach out.
Top TV Stations in Tanzania
Television in Tanzania is a mass-reach medium, and the competitive landscape at the top is tight. The Top 5 stations are separated by only four percentage points on reach, with Azam Two leading by a narrow margin over ITV, the two Azam Sports channels, and TBC1.
Top 10 TV Stations by Reach (January – March 2026)
One of the most striking features of the Tanzanian list is how much of it belongs to a single broadcaster group. Azam Media occupies three of the Top 5 positions on reach (Azam Two, Azam Sports 1, Azam Sports 2) and a fourth in the Top 10. This cluster gives the group an unusually strong position in any national reach calculation and a near-unavoidable presence in sports-led media plans.
TV Viewership by Dayparts
Reach tells us who tuned in over the quarter. Daypart share of viewing tells us when each station was winning. The numbers below represent each station’s share of total Top 10 viewing within the time block.
- Early Morning (6:00 AM – 9:00 AM): Breakfast TV is the most fragmented block of the day. TBC1 leads with 16% share of Top 10 morning viewing, with ITV (15%), Clouds (12%), and Azam Two (11%) close behind. Seven different stations hold between 8% and 16%, which means morning audiences in Tanzania are genuinely split across the dial rather than concentrated on one or two options.
- Afternoon (4:00 PM – 6:00 PM): This is where the Azam Sports effect becomes very clear. Azam Sports 1 commands 37% of Top 10 viewing in this block, and when combined with Azam Sports 2 and SuperSport, sports channels take more than 60% of all Top 10 afternoon viewing. Live football and pre-match programming drive this concentration, and it is one of the most commercially distinct dayparts in the Tanzanian market.
- Prime-Time (7:00 PM – 10:00 PM): This is the single most important commercial block of the day, and it is dominated by three names. Azam Sports 1 takes 20% share, followed by ITV (16%) and Azam Sports 2 (15%). The Azam cluster combined (including Azam Two at 12%) takes roughly 47% of all Top 10 prime-time viewing, which is one of the most concentrated prime-time positions of any East African market.
Weekday Prime-Time Share of Viewing (7:00 PM – 10:00 PM)
Late Night (10:00 PM – Midnight): The sports channels extend their lead into late-night viewing. Azam Sports 1 (29%) and Azam Sports 2 (20%) together account for nearly half of all late-night Top 10 viewing, with Azam Two adding another 16%. Late-night in Tanzania is, effectively, a sports block.
Weekend and Special Programming Trends
Weekends amplify what is already true about weekday viewing in Tanzania: the evening peak becomes even sharper, and the sports channels maintain their structural advantage across the day.
- ITV leads weekend prime-time with 22% share, reflecting the pull of local drama and entertainment programming on Saturday and Sunday evenings.
- The 8:00 PM weekend half-hour is by far the largest viewing window in the week, with total Top 10 audience roughly 1.6× the next-largest weekend half-hour and well above any single weekday moment.
- Morning reach is significantly larger on weekends, with the 6:30 AM block drawing audiences that rival mid-afternoon weekday numbers. This suggests weekend morning content (children’s programming, religious broadcasts, magazine shows) remains a meaningful commercial window.
Top Radio Stations in Tanzania
Radio in Tanzania is concentrated at the top to a degree that is rare in the region. Three stations account for the bulk of national listening, and the drop-off from third to fourth place is the steepest on the chart.
Top 10 Radio Stations by Reach (January – March 2026)
TBC Taifa Radio leads at 47%, followed by Clouds (44%) and Radio Free Africa (38%). The gap to the fourth station, Wasafi FM, is more than 12 percentage points. For national advertisers, this concentration means that the top three stations are effectively must-include for any broad-reach Tanzanian radio plan.
Radio Listenership by Dayparts
Breakfast (6:00 AM – 9:00 AM): The breakfast block is dominated by the top three. TBC Taifa Radio leads with 26% share of Top 10 morning listening, followed by Radio Free Africa (22%) and Clouds (18%). Together, these three stations account for roughly two-thirds of all Top 10 breakfast listening on weekdays.
Weekday Breakfast Share of Listening (6:00 AM – 9:00 AM)
Daytime (9:00 AM – 4:00 PM): Listening levels dip after breakfast but stabilise through the middle of the day, with Clouds holding a particularly strong position in the late-morning and lunchtime blocks. Radio Free Africa also sustains strong midday listening, reflecting loyal audiences who stay tuned through the workday.
Drive-Time (4:00 PM – 7:00 PM): The afternoon drive block tightens the race. TBC Taifa Radio (24%) holds a narrow lead over Clouds (22%) and Radio Free Africa (20%), with Wasafi FM (10%) a clear fourth. The top three are separated by less than five percentage points during drive-time, making it one of the most competitive listening windows of the day.
Evening (7:00 PM – 10:00 PM): The evening sees TBC Taifa Radio and Clouds move essentially level at roughly 26% share each, with Radio Free Africa dropping back to 12%. This is also where Wasafi FM’s 9:00 PM spike shows up, reflecting its entertainment-led evening programming pulling a distinct audience segment.
Weekend Radio Trends
Weekend listening follows a similar shape to weekdays but with a flatter distribution across the day. TBC Taifa Radio remains the weekend leader at breakfast, and Radio Free Africa’s weekend breakfast position strengthens, reflecting the role of weekend talk and religious programming.
Insights from the Q1 2026 Tanzania Media Numbers
A few structural themes emerge from the Tanzanian data:
- Prime-time has a single peak, and it is unusually sharp. The 8:00 PM half-hour on weekdays is more than 1.5× the size of any other weekday moment, and on weekends it is even larger. Unlike markets with multiple evening peaks, Tanzania concentrates its evening audience into one narrow window. This is an important peak for media plans.
- Sports is a structural pillar of Tanzanian TV, not a niche category. Azam Sports 1 alone takes more than a third of afternoon viewing and a fifth of prime-time viewing. Any national media plan that excludes sports inventory is effectively excluding a major portion of the available TV audience.
- Breakfast is bigger than drive-time on radio, by a wide margin. Total Top 10 radio listening at 6:00 AM on weekdays is roughly 4× the level at 5:00 PM. This is a common pattern, but Tanzania’s morning peak is especially concentrated into the 6:00 – 7:00 AM hour. For advertisers, the morning hour is the single most valuable radio block of the day.
- Radio listening is more concentrated than TV viewing. Three stations account for the majority of national radio listening across every daypart, while TV’s Top 10 is more evenly distributed. Advertisers can build meaningful TV reach across five or six channels, but radio reach in Tanzania requires the top three.
- Cluster-brand effects matter more here than elsewhere. The Azam cluster’s combined share of prime-time TV viewing (around 47%) is a pattern that does not appear in most other East African markets. For competing broadcasters, advertisers, and media regulators, the shape of the market is not just about individual station performance but about group-level concentration.
GeoPoll Audience Measurement
GeoPoll provides real-time, data-driven insights into media consumption in Tanzania and across more than 120 countries. Whether you need daily audience measurement, on-demand analytics, a campaign effectiveness study, or a custom report covering a specific audience segment or time period, GeoPoll Audience Measurement gives broadcasters, advertisers, and media planners the tools to make informed decisions.
How to access more insights:
- Subscribe for daily TV and radio ratings to track audience behavior in real time
- Request a custom report for any time period or audience segment
- Measure advertising impact and campaign performance
- Analyze viewership trends by content type, daypart, and broadcaster
The post The Top TV and Radio Stations in Tanzania – Q1 2026 appeared first on GeoPoll.
]]>The post The Top TV and Radio Stations in Kenya – Q1 2026 appeared first on GeoPoll.
]]>GeoPoll’s Audience Measurement (GAM) data from January to March 2026 gives us a clear picture of who is watching, who is listening, and when. This report distills the Q1 2026 numbers into the trends that matter for broadcasters, advertisers, and media planners.
As you read through this overview, remember that this is a high-level summary of national reach and share for Q1 2026. Weekly and monthly shifts, regional breakdowns, content-level performance, advertising effectiveness studies, hourly unique-audience analysis, demographics, and actual numbers are not covered here. For deeper insights, please reach out.
Top TV Stations in Kenya
Television remains a mass-reach medium in Kenya, and the top of the table in Q1 2026 looks familiar. Citizen TV held on to the number one position, reaching three in every four Kenyan TV viewers over the quarter. NTV, KTN, SuperSport, and TV 47 rounded out the Top 5, with SuperSport’s continued climb into the top tier showing both the strength of live sport and the appetite for premium football programming.
Top 10 TV Stations by Reach (January – March 2026)
A few things stand out when compared to our previous report. SuperSport has climbed into the Top 4 on the back of a packed sporting calendar. TV 47 continues to consolidate its position as a go-to news and current affairs option, and Al Jazeera’s appearance in the Top 10 reflects strong interest in international news coverage during an eventful first quarter, especially with the Iran-Israel-US conflict.
TV Viewership by Dayparts
Reach tells us who tuned in over the quarter. Daypart share of viewing tells us when each station was winning. The numbers below represent each station’s share of total Top 10 viewing within the time block.
Early Morning (6:00 AM – 9:00 AM): Breakfast TV belongs to Citizen TV, which captures roughly 26% of Top 10 viewing during the morning block. NTV follows at 11.5%, with TV 47, KTN, and K24 clustered closely as Kenyans catch up with morning bulletins and talk shows before heading out.
Mid-Morning to Afternoon (9:00 AM – 6:00 PM): The daytime block is fragmented. Citizen TV still leads, but Maisha Magic East makes a strong showing with local drama and soap operas pulling in at-home audiences, while Inooro TV sustains a loyal vernacular following.
Prime-Time (7:00 PM – 9:30 PM): This remains the most competitive and most commercially valuable block of the day. Citizen TV commands 35.5% of Top 10 prime-time viewing on weekdays, powered by the 7:00 PM Swahili news and the programming that follows. NTV (13.4%) is the clear number two, followed by Maisha Magic East (8.9%), KTN (8.5%), SuperSport (7.3%), and TV 47 (6.9%).
Weekday Prime-Time Share of Viewing (7:00 PM – 9:30 PM)
Late Night (10:00 PM – Midnight): This is where the ranking changes most dramatically. SuperSport takes 37% of late-night viewing on weekdays, often more than any other station, as football fans stay up for European fixtures. Citizen TV holds second place at about 21%, with Maisha Magic East third.
Weekend and Special Programming Trends
Weekends shuffle the deck in favour of sport and family programming.
- SuperSport’s share of weekend prime-time viewing climbs to 16.9%, nearly double its weekday prime-time share, driven by weekend football and other live sports.
- In the weekend afternoon block (2:00 PM – 6:30 PM), SuperSport and Citizen TV run neck and neck, each capturing roughly 22–23% of Top 10 viewing, a pattern that reflects sports coverage running alongside family viewing.
- Maisha Magic East maintains a strong weekend footprint with local drama.
- Citizen TV and NTV continue to anchor weekend news bulletins and current affairs panels.
Top Radio Stations in Kenya
Radio continues to be remarkably resilient in Kenya. Despite the trends around podcasts and social audio, nearly two in three Kenyan radio listeners tuned into Citizen Radio in Q1 2026, with a dense pack of competitors close behind.
Top 10 Radio Stations by Reach (January – March 2026)
The top four stations are separated by a narrow margin, and all of them recorded their peak audiences at 7:00 AM – confirming that breakfast radio remains the most valuable block on the dial as listeners commute to work. Radio Jambo, interestingly, is the only Top 10 station whose peak hour shifts to 8:00 AM, pointing to a later-starting commuter audience, probably driven by the popular Patanisho segment.
Radio Listenership by Dayparts
Breakfast (6:00 AM – 9:00 AM): The breakfast block is a four-station contest. Classic 105 leads with 18.8% of Top 10 morning listening on weekdays, narrowly edging Citizen (17.4%), Radio Jambo (15.0%), and Radio Maisha (12.0%). Lifestyle and political talk shows drive this block, and it is where brands typically invest most heavily.
Weekday Breakfast Share of Listening (6:00 AM – 9:00 AM)
Daytime (9:00 AM – 4:00 PM): Listening levels dip compared to breakfast, but Citizen and Classic 105 continue to lead. Kameme shows particular strength in the mid-morning block, reflecting its loyal Central Kenya audience staying tuned through the day.
Drive-Time (4:00 PM – 7:00 PM): Citizen pulls ahead in the afternoon drive block with 20.4% share of Top 10 listening, followed by Classic 105 (14.5%), Radio Jambo (14.1%), and Radio Maisha (11.9%).
Evening (7:00 PM – 10:00 PM): Citizen’s lead widens further in the evening to 26.1%, with Classic 105, Radio Maisha, and Radio Jambo filling out the top four.
Weekend Radio Trends
The weekend pattern mirrors weekdays at the top, but with a gentler peak and more even distribution across the day. Citizen (19.3%) and Classic 105 (18.1%) are essentially tied for weekend breakfast leadership, while Radio Jambo and Radio Maisha maintain their strong third and fourth positions.
What the Q1 2026 Numbers Tell Us
A few themes emerge from the data:
-
The gap behind the leaders is narrower than the top line suggests. Citizen TV and Citizen Radio lead their respective rankings. It is worth noting that in several dayparts, the second and third-place stations are within single-digit share points, meaning daypart selection matters as much as station selection for most campaigns for media planners.
- Sport is now a Top 10 force on television. SuperSport’s weekend prime-time share (16.9%) and late-night dominance (37%) signal that live sports are among the few categories consistently pulling Kenyan viewers back to linear TV.
- Breakfast remains the most contested slot on radio. Four stations are within a seven-point range at breakfast, and any share shift during this block has outsized commercial implications.
- Vernacular and international stations have real weight. Inooro TV, Kameme, and Al Jazeera all made meaningful appearances in national rankings and in specific dayparts, a reminder that Kenya’s media market is more nuanced than the top line suggests.
GeoPoll Audience Measurement
GeoPoll provides real-time, data-driven insights into media consumption in Kenya and across more than 120 countries. Whether you need daily audience measurement, on-demand analytics, a campaign effectiveness study, or a custom report covering a specific audience segment or time period, GeoPoll Audience Measurement gives broadcasters, advertisers, and media planners the tools to make informed decisions.
How to access more media insights for Kenya:
- Subscribe for daily TV and radio ratings to track audience behavior in real time
- Request a custom report for any time period or audience segment
- Measure advertising impact and campaign performance
- Analyze viewership trends by content type, daypart, and broadcaster
The post The Top TV and Radio Stations in Kenya – Q1 2026 appeared first on GeoPoll.
]]>The post The Price of Conflict: How the Iran-Isreal-U.S. War is Affecting Fuel Costs and Supply and Cost of Living appeared first on GeoPoll.
]]>The Iran–Israel–United States conflict has been reshaping global energy markets since late 2025. For citizens in the Global South, the consequences are neither abstract nor distant. In Pakistan, the government implemented a historic Rs 55 per litre fuel price increase on 6 March 2026. In Kenya, the Energy and Petroleum Regulatory Authority (EPRA) announced on 14 April 2026 the largest fuel price adjustment in over 21 years of regulatory records — a KSh 28.69 per litre increase for petrol and KSh 40.30 for diesel, effective 15 April. In Egypt, subsidised fuel prices were revised upward for the third time in twelve months. In South Africa, the inland price of 95-octane petrol is set to breach some of the highest prices ever seen in the country . These are not coincidences. They are the downstream effects of a single geopolitical shock.
In early March 2026, GeoPoll surveyed 3,754 citizens across Egypt, Kenya, Nigeria, Pakistan, Saudi Arabia, and South Africa as part of our Caught in the Crossfire? citizen perceptions study. Among the study’s most striking findings: the economic dimension of the conflict is being felt acutely and immediately, with fuel prices at the centre of public concern.
| 70% | of respondents across all six countries report that the conflict has affected fuel prices in their country |
Across the six-country sample, 70% of respondents report that the conflict has affected fuel prices in their country, with 42% characterising the impact as significant. The finding is consistent across diverse economic contexts – from oil-importing economies such as Pakistan and Kenya to the oil-exporting economy of Saudi Arabia, where 46% still report an impact.
The variation across countries reflects both the degree of energy dependence and the extent of government intervention. Pakistan, where the government passed through the full cost of disrupted imports, registers the highest impact at 85%. Saudi Arabia, which benefits from domestic production and price controls, registers the lowest at 46% – though this figure is notable in itself for a major oil producer.
Respondents Reporting or expecting Fuel Price Impact by Country
Country Analysis: The Fuel Crisis on the Ground
Pakistan: The Highest Impact in the Dataset
Pakistan registers the most severe fuel price impact of any country in the study, with 85% of respondents reporting or expecting an effect. The finding is consistent with on-the-ground realities: on 6 March 2026, the government implemented a Rs 55 per litre fuel price increase – among the largest single adjustments in the country’s recent history – directly attributed to rising import costs resulting from conflict-related supply disruptions.
| 85% | of Pakistani respondents report or expect fuel price impact – the highest of any country surveyed |
Fifty percent of Pakistani respondents identify inflation and cost of living as the single most significant economic consequence of the conflict, the highest figure for any country on this measure. Pakistan’s dependence on imported crude oil, combined with a depreciating rupee and constrained foreign exchange reserves, creates a transmission mechanism that converts global oil price shocks directly into consumer-level inflation.
Pakistan also brokered the short-lived ceasefire between Iran and the United States that took effect on 8 April 2026 before collapsing on 12 April. The ceasefire’s failure has further complicated Pakistan’s diplomatic positioning and reinforced public anxiety about prolonged economic disruption.
Kenya: From Shortage to Record-Breaking Price Adjustment
Kenya presents a particularly instructive case study. At the time of surveying in March 2026, Kenya’s fuel prices were government-regulated through the EPRA pricing mechanism, which had effectively absorbed global price increases without passing them to consumers. However, 79% of Kenyan respondents still reported fuel price impact – because the economic strain was manifesting not through prices but through supply disruptions.
By early April, a severe fuel shortage had spread across at least 13 counties. In response, the government deployed KSh 6.2 billion in emergency subsidies and reduced VAT on fuel from 16% to 13%. These measures proved insufficient to contain the crisis.
On 14 April 2026, EPRA announced the largest fuel price adjustment in over 21 years of regulatory records: super petrol now retails at KSh 206.97 per litre in Nairobi, up KSh 28.69 from KSh 178.28, while diesel rises KSh 40.30 to an all-time high of KSh 206.84, effective 15 April. EPRA data indicate that the landed cost of imported super petrol rose 41.5% and diesel 68.7% during the review period. The regulatory body cited “significant increases in the prices of petroleum products in the international market” as the primary driver.
The magnitude of these adjustments points to the unsustainability of shielding consumers from global price shocks through regulation alone, and validates the concerns expressed by the 79% of Kenyan respondents who identified fuel price impact before the price adjustment was officially announced.
| 79% | of Kenyan respondents reported fuel impact even before the record April price hike |
Egypt: Inflation Compounds an Existing Crisis
Seventy-eight percent of Egyptian respondents report fuel price impact. Egypt, which floated its currency in March 2024 and has experienced sustained inflationary pressure, is particularly vulnerable to energy price shocks. The government has raised subsidised fuel prices three times in the past twelve months. Brent crude’s rise from approximately $70 per barrel in late 2025 to over $128 per barrel in March 2026 has placed severe strain on Egypt’s import bill and fiscal position.
Forty-eight percent of Egyptian respondents cite inflation as the most significant economic consequence – the second-highest figure after Pakistan (50%). Nineteen percent identify food prices specifically, the highest of any country, reflecting the compounding effect of energy costs on food production and transport.
South Africa: A Slow-Burning Crisis
Sixty-eight percent of South African respondents report fuel price impact. The inland price of 95-octane petrol exceeded R30 per litre in March 2026. South Africa’s fuel pricing mechanism adjusts monthly based on international crude prices, the rand–dollar exchange rate, and shipping costs – all three of which have moved unfavourably. The Automobile Association of South Africa warned in April that further significant increases are expected for May 2026.
Twenty-two percent of South African respondents cite employment and job losses as the most significant economic consequence – the highest figure for any country on this measure – reflecting broader structural vulnerabilities in an economy already contending with 32% unemployment.
Nigeria: A Producer Still Feeling the Pressure
Despite being Africa’s largest oil producer, 56% of Nigerian respondents report fuel price impact. Nigeria’s Dangote refinery, which began operations in late 2024, has partially insulated the domestic market from global price shocks. However, the naira’s weakness and continued import dependence for refined products mean that global price movements still transmit to consumers, albeit with a lag.
The relatively lower figure compared to other countries in the sample may reflect some insulating effect of domestic production, but 56% still represents a majority reporting impact – a finding that challenges any assumption that oil-producing nations are immune to the conflict’s economic consequences.
Saudi Arabia: Impact Even for the Region’s Largest Producer
Saudi Arabia registers the lowest fuel price impact at 46%, consistent with its position as the world’s largest oil exporter with heavily subsidised domestic fuel prices. That nearly half of Saudi respondents still report an impact suggests the conflict’s economic effects extend beyond fuel pricing to broader cost-of-living increases and market uncertainty.
Inflation is the Primary Economic Consequence
When asked to identify the single most significant economic consequence of the conflict, respondents across all six countries point to inflation and cost of living (43%), followed by fuel prices specifically (27%), food prices (15%), and employment or job losses (13%). The pattern is consistent across countries, though the relative weighting varies with national economic conditions.
| Economic Impact | Pakistan | Egypt | Kenya | S. Africa | Nigeria | Saudi |
| Inflation / CoL | 50% | 48% | 40% | 38% | 35% | 42% |
| Fuel prices | 30% | 22% | 33% | 25% | 30% | 22% |
| Food prices | 10% | 19% | 14% | 12% | 16% | 15% |
| Employment | 8% | 9% | 11% | 22% | 16% | 18% |
The Strait of Hormuz: A Global Chokepoint Under Pressure
The economic dynamics documented in this study are inseparable from developments in the Strait of Hormuz, through which approximately 20% of the world’s daily oil supply transits. Following the collapse of the Pakistan-brokered ceasefire on 12 April 2026, the U.S. Navy intensified its maritime operations in the Persian Gulf, raising the operational risk premium on all crude oil shipped through the strait.
Brent crude prices rose from approximately $70 per barrel in late 2025 to over $128 per barrel by mid-March 2026. While prices have fluctuated with diplomatic developments, the U.S. Energy Information Administration’s revised 2026 forecast of $96 per barrel (up from $74) signals that markets anticipate sustained disruption. For import-dependent economies such as Pakistan, Kenya, and Egypt, each dollar increase in the Brent price translates directly into higher landed costs for fuel, food, fertiliser, and manufactured goods.
Citizen Perspectives
The survey included open-ended responses that contextualise the quantitative findings. The following responses are representative of the concerns expressed across the six-country sample:
| “It’s worrisome as we are in alliance with the States so we could be hit next.”
— Respondent, Pakistan |
| “The price of fuel in South Africa is too high and it has a direct impact on the cost of food and other essential commodities.”
— Respondent, South Africa |
| “The war in the Middle East has made food items and fuel too expensive for the common man.”
— Respondent, Nigeria |
Why This Matters
The data presented in this report demonstrate that the Iran–Israel–U.S. conflict is not merely a geopolitical crisis confined to the Middle East. It is an economic event with measurable, immediate consequences for populations across the Global South. The 70% of respondents reporting fuel price impact, the 92% expressing cost-of-living concern, and the cascading effects on food, transport, and employment represent a humanitarian and policy challenge that extends well beyond the direct conflict zone.
For policymakers, the findings underscore the limits of domestic price controls and subsidies in the face of sustained global energy price shocks. Kenya’s trajectory, from regulated prices to nationwide shortage to record-breaking price adjustment, illustrates the unsustainability of shielding consumers indefinitely from global market forces.
For international organisations and development agencies, the data provide an empirical basis for understanding how distant conflicts translate into lived experience for citizens in Africa, South Asia, and the Middle East. The economic consequences documented here are likely to intensify if the conflict continues or escalates.
Methodology
This report draws on data from GeoPoll’s Caught in the Crossfire? citizen perceptions study, conducted in early March 2026. The study surveyed 3,754 respondents across six countries: Egypt (n = 626), Kenya (n = 627), Nigeria (n = 625), Pakistan (n = 626), Saudi Arabia (n = 624), and South Africa (n = 626).
Respondents were recruited through GeoPoll’s proprietary mobile panel, which uses random sampling from mobile network operator databases to reach nationally representative populations. Surveys were administered via mobile-based interviewing across multiple modes, including CATI, SMS, and mobile web. All respondents were aged 18 and above.
The margin of error for country-level estimates is approximately ±3.9% at a 95% confidence level. Cross-country comparisons should be interpreted with awareness of differing national contexts, including variation in government fuel pricing policies, currency stability, and import dependence.
Access the full 37-page report:
Caught in the Crossfire? A Six-Country Citizen Perceptions Study on the Iran–Israel–U.S. Conflict
For enquiries about country-specific data, custom analysis, or partnership opportunities, contact us.
The post The Price of Conflict: How the Iran-Isreal-U.S. War is Affecting Fuel Costs and Supply and Cost of Living appeared first on GeoPoll.
]]>The post Pakistan: Caught in the Iran-Israel-US Crossfire? appeared first on GeoPoll.
]]>Pakistan occupies a unique position in the Iran–Israel–U.S. conflict. As Iran’s immediate neighbour, a nuclear-armed state, a major recipient of Chinese investment through CPEC, and a long-standing U.S. security partner, it sits at the intersection of every fault line this conflict has exposed. In early March 2026, GeoPoll surveyed 626 Pakistani citizens as part of a broader six-country study. The results reveal the most polarised and consistently intense responses of any country in the dataset.
Who Is to Blame for the Conflict? Israel, Overwhelmingly
Sixty-three percent of Pakistani respondents hold Israel most responsible for the conflict – the highest figure for any country in the survey and nearly double the six-country average (38%). A further 20% blame the United States, while only 5% point to Iran. The framing is clear: for most Pakistanis, this is a war waged by Israel and the U.S., not against them.
63%
of Pakistanis blame Israel: the highest of any country surveyed
Sympathy Tilts Sharply Toward Iran
Related to the finding above, Pakistan registers the strongest pro-Iran sympathy in the dataset at 82% – nearly double the overall average of 43% and the single highest figure for any question-country combination in the study. Just 3% express sympathy for Israel. This reflects deep religious and cultural affinity, shared borders, and decades of people-to-people ties. It is also consistent with Pakistan’s diplomatic positioning, which has historically sought to balance its Western security partnerships with its identity as a Muslim-majority state.
Fear of Escalation Is Acute
Eighty-six percent of Pakistani respondents believe the conflict could lead to a wider global war, which is not abstract anxiety. Pakistan shares a border with Iran, has its own nuclear arsenal, and is acutely aware that regional escalation could draw it in directly. The nuclear dimension resonates deeply, with 70% of respondents across all six countries view nuclear weapons use as likely, and Pakistan’s own nuclear status makes this fear personal rather than theoretical.
86%
fear the conflict could escalate into a global war
Pakistan is Experiencing the Worst Economic Pain
Pakistan reports the most severe economic impact of any country surveyed. Eighty-five percent say the conflict has significantly affected fuel prices, consistent with the government’s historic Rs 55 per liter fuel price hike on 6 March 2026, directly attributed to regional supply disruptions. Fifty percent cite inflation and cost of living as the single most significant economic consequence, the highest of any country.
Nearly three-quarters (73%) of Pakistani respondents report some form of personal impact from the conflict, far exceeding any other country. As one respondent put it: “It’s worrisome as we are in alliance with the States so we could be hit next.”
A Geopolitical Realignment: China Up, U.S. Complicated
Pakistan’s relationship with global powers is shifting. Forty-four percent now view China more favourably as a result of the conflict – the largest positive shift of any country – and 49% trust China most to act in Pakistan’s and the world’s interests. This is more than double any other country-body combination except Kenya’s and Nigeria’s trust in the UN.
Views of the U.S. are more nuanced than might be expected. While 33% view the U.S. less favourably, an equal 33% say their view is unchanged, and 20% actually view the U.S. more favourably. Pakistan is the only country where a significant share (39%) believes the U.S. is primarily serving Israel’s interests rather than its own.
Russia also benefits: 33% of Pakistanis view Russia more favourably, the highest positive shift for Russia in the dataset. China’s non-interventionist positioning and its deep economic ties through CPEC are clearly paying reputational dividends.
What Pakistani Citizens Want: Peace – and Support for Iran
Pakistan is the only country in the survey where a large share (42%) explicitly wants their government to support Iran, nearly equalling the 44% who call for peace negotiations. In every other country, peace negotiations command a clear majority. This split reflects the depth of religious and geopolitical solidarity with Iran, and suggests that any Pakistani government response perceived as neutral or Western-aligned could face significant public backlash.
On institutional trust, 35% look to the UN and 31% to China as most capable of resolving the conflict. Only 9% trust the United States. As one respondent noted: “Our country Pakistan is still sitting silent and foreign policy support is neutral.”
When asked which country or international body they trust most to act in the best interests of Pakistan and the world, China was, interestingly, overwhelmingly the most trusted (49%) – over twice that of even the United Nations.
Why This Matters
Pakistan’s profile in this data is the most extreme and internally consistent of any country surveyed. The combination of overwhelming blame on Israel, near-universal sympathy for Iran, the highest economic pain, the strongest China alignment, and the most acute fears of global escalation paints a picture of a population that feels deeply, personally affected by a conflict in which it has no formal role.
For policymakers and international organizations, the implications are clear. Pakistan’s public opinion is not a passive backdrop – it is a force that shapes the government’s room to maneuver on foreign policy, alliance decisions, and economic stabilization. Any diplomatic strategy that ignores this sentiment risks misreading one of the most consequential populations in the conflict’s broader orbit.
Methodology
This report draws on data from GeoPoll’s multi-country online survey conducted in the first week of March 2026, during a period of active military escalation in the Middle East following the launch of U.S.-Israeli Operation Epic Fury on 28 February 2026.
The survey collected 3,754 responses across six countries: Egypt, Kenya, Nigeria, Pakistan, Saudi Arabia, and South Africa. The Pakistan subsample comprises 626 respondents. Respondents were recruited through GeoPoll’s online panel and surveyed via a structured questionnaire covering conflict awareness, attribution, sympathy, escalation concerns, economic impact, views on global powers, institutional trust, media consumption, personal security, and preferred government responses. GeoPoll administered the questionnaire in both English and Urdu in Pakistan.
All percentage figures are rounded to the nearest whole number. Country-level breakdowns are unweighted.
Read the full 37-page report
This is a sub-report of GeoPoll’s report, “Caught in the Crossfire?“ A Six-Country Citizen Perceptions Study on the Iran–Israel–U.S. Conflict.
To read the full 37-page report, including detailed cross-country comparisons, verbatim citizen voices, and policy recommendations, visit: www.geopoll.com/blog/iran-israel-us-conflict-report
For enquiries about country-specific data, custom analysis, or partnership opportunities, contact [email protected]
The post Pakistan: Caught in the Iran-Israel-US Crossfire? appeared first on GeoPoll.
]]>